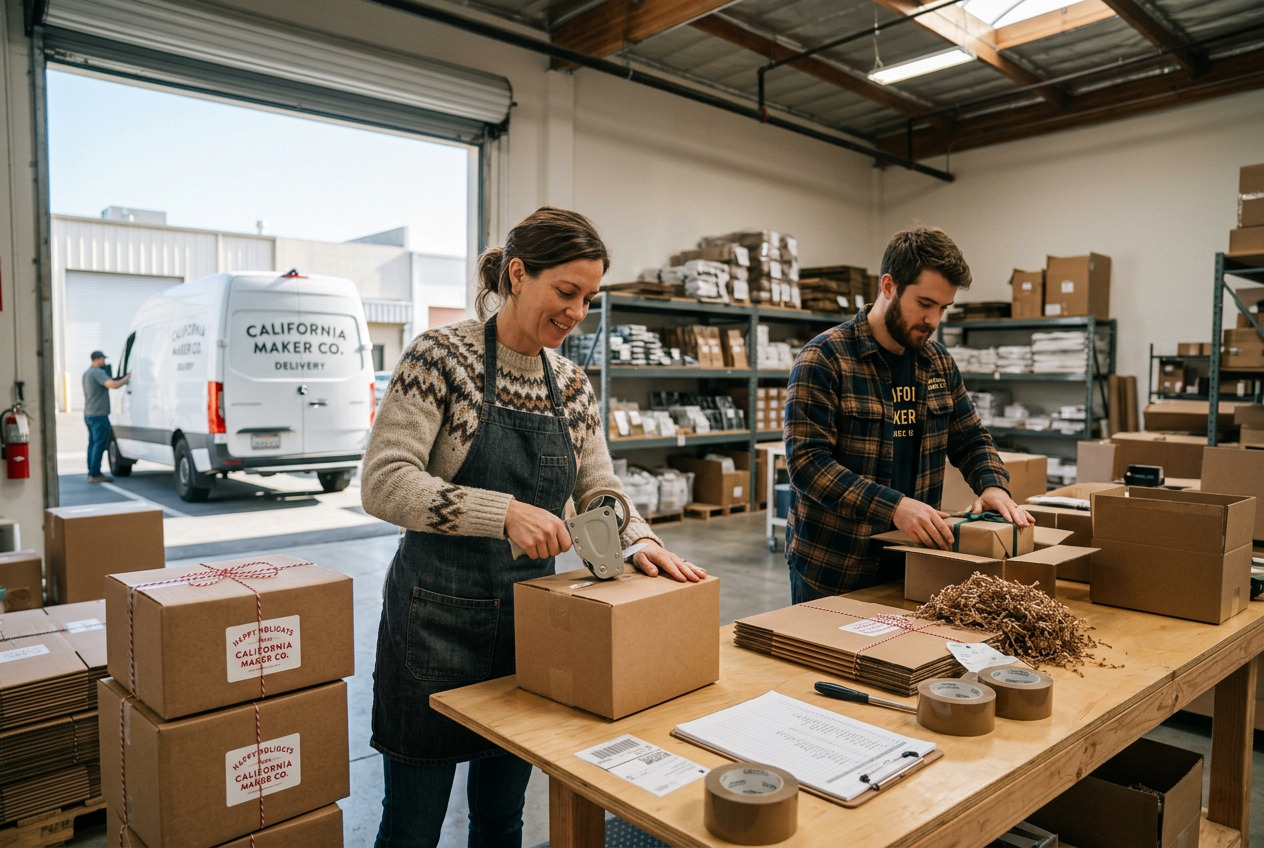
The holiday season is a bustling time for California businesses, from small retailers to e-commerce stars and local delivery services. Thriving sales periods bring a surge of customer orders, more shipments, and additional delivery demands. But while the holiday rush boosts revenue, it also brings increased risks—packages may get lost, goods can be damaged in transit, and delivery-related accidents might occur.
Are your holiday deliveries covered by business insurance? The answer depends on the type of loss, how products are transported, and the specific coverage in your commercial insurance policies. Reviewing your business insurance for holiday deliveries before the season ramps up can be essential to identifying potential risks, plugging coverage gaps, and protecting your business from unexpected financial headaches.
Does Business Insurance Cover Holiday Deliveries?
Standard business insurance policies do not automatically cover every potential loss tied to holiday shipping and delivery. Whether you’re dispatching packages via a third-party carrier, operating your own delivery vehicles, or hiring temporary delivery drivers, your insurance coverage may include limits, exclusions, or specific policy requirements. Understanding how different insurance protections apply to shipping and delivery scenarios can help you better manage seasonal risks.
Commercial Property Insurance and Goods in Transit
Commercial property insurance typically protects business assets against specified risks like fire, theft, or vandalism. However, once inventory leaves your premises, that coverage may no longer apply. For instance, a California specialty goods retailer with inventory insured on-site may find their standard property coverage insufficient if packages go missing during delivery.
For such situations, goods in transit insurance is designed to help. Often included as part of inland marine coverage or transportation policies, this protection covers specific losses to merchandise while it’s being transported. Policies vary, so it’s important to confirm which transportation methods, property types, and causes of loss are covered—and whether geographic limits impact your protection.
Why Shipping Arrangements Matter
How your business handles shipping can impact where responsibilities lie in the event of lost, stolen, or damaged goods. Your coverage can depend on whether you:
- Use a third-party shipping carrier.
- Deliver orders using company vehicles.
- Hire a local courier service or independent drivers.
- Rely on employees and personal vehicles for deliveries.
For example, shipping contracts often outline liability and claim processes should the carrier lose or damage packages. Before holiday sales ramp up, assess both your shipping agreements and your business insurance to clarify where gaps may exist.
What Happens if Holiday Packages Are Lost, Stolen, or Damaged?
Despite your best planning, packages can still encounter issues during the holiday shipping frenzy. Consider these common problems:
- Damaged shipments: Fragile products may not survive transit without adequate packaging or careful handling.
- Lost merchandise: Packages may never reach their destination due to errors or theft.
- Stolen deliveries: Goods left unattended outside a customer’s home might be targeted.
- High-value losses: Expensive shipments exceeding carrier liability limits create potential financial strain.
Understanding Shipping Insurance and Carrier Liability
Many shipping carriers offer liability protections or optional shipping insurance for their services. However, carrier liability terms often provide limited compensation based on declared package values, specific exclusions, or cumbersome claim processes.
For example, a California online shop selling electronics may ship several high-value gadgets during the holidays. If one is lost in transit, the carrier’s liability might only cover a portion of the device’s worth. That’s where goods in transit insurance may step in to supplement—and it’s why understanding your coverage limits and exclusions matters.
Review Coverage Limits for Valuable Shipments
Businesses shipping high-ticket items like electronics, jewelry, or specialty equipment should pay special attention to coverage limits and deductible amounts. Accurate documentation, such as shipment tracking, photos, and detailed records, can streamline any claims process.
Are Delivery Vehicles and Drivers Properly Insured?
When your business delivers products, it’s not just about securing the merchandise. You’ll also need to address risks related to the vehicles and people involved in transportation.
Commercial Auto Insurance for Business Deliveries
If your company owns and operates vehicles for deliveries, commercial auto insurance is essential. This policy may include liability protection for accidents, physical damage protection for insured vehicles, and injury-related benefits, depending on your coverage. However, it’s important to note that insuring your vehicles doesn’t necessarily mean the merchandise inside them is covered during an incident. Separate property or cargo-specific insurance may still be needed.
For example, a California bakery uses a company van to send out fresh holiday orders. If an accident occurs en route and damages another vehicle, the van’s commercial auto liability insurance could cover eligible third-party damages. But replacing the ruined baked goods might require additional coverage outside the auto policy.
What if Employees Use Their Personal Vehicles?
Many holiday delivery arrangements involve employees using their own vehicles. However, a standard personal auto insurance policy may limit or exclude coverage for certain business or delivery-related activities. To address these gaps, businesses can explore hired and non-owned auto insurance, a liability-focused commercial policy that helps cover such situations.
Keep in mind that this type of insurance generally doesn’t cover the employee’s vehicle or the contents being transported. Accurate disclosure of delivery activities to insurance providers ensures adequate coverage and avoids hidden risks.
Understand Liability Risks When Using Third-Party Delivery Services
Outsourcing deliveries to third-party providers doesn’t always eliminate your liability. Even with a carrier handling holiday deliveries, your business can remain exposed to financial risks.
Review Contracts With Delivery Providers
When partnering with shipping carriers or logistics companies, business owners should review contract terms covering:
- Delivery responsibilities.
- Compensation for package losses or damages.
- Insurance requirements and indemnification clauses.
These agreements vary, but understanding your obligations can help prevent disputes and solidify your risk management plan.
Know What General Liability Insurance May Cover
Commercial general liability insurance helps protect businesses against third-party property damage or bodily injury claims. For instance, an accident during a delivery involving damaged customer property might raise liability questions. However, not every delivery-related issue, such as damaged product claims, would fall within general liability policy terms. Distinguishing between liability insurance and other protections like commercial auto or carrier insurance is key.
Holiday Delivery Insurance Checklist for California Small Businesses
Here’s what to review before the seasonal rush:
- Evaluate current business insurance: Confirm property, liability, and auto coverages.
- Check transit protection: Verify goods-in-transit, inland marine insurance, or endorsements.
- Understand shipping terms and carrier liability: Align loss values with compensation limits.
- Review delivery vehicles: Ensure insurance meets the needs of company vehicles.
- Discuss employee personal vehicle use: Confirm hired and non-owned auto coverage.
- Examine third-party logistics contracts: Clarify shipping responsibilities and liabilities.
- Keep accurate records: Maintain shipment receipts, tracking data, and relevant proof.
- Consult an expert: Talk with an insurance professional about seasonal delivery risks.
Planning ahead not only reduces risk but ensures your business stays on track during its busiest time of the year.
Protect Your Holiday Deliveries With UNISERV
Holiday shipping and delivery activities can expose businesses to risks that aren’t always addressed by standard insurance policies. Whether you need protection for transported goods, delivery vehicles, or liability concerns, reviewing your insurance coverage now is critical to staying protected.
At UNISERV, we specialize in personalized commercial insurance solutions for California