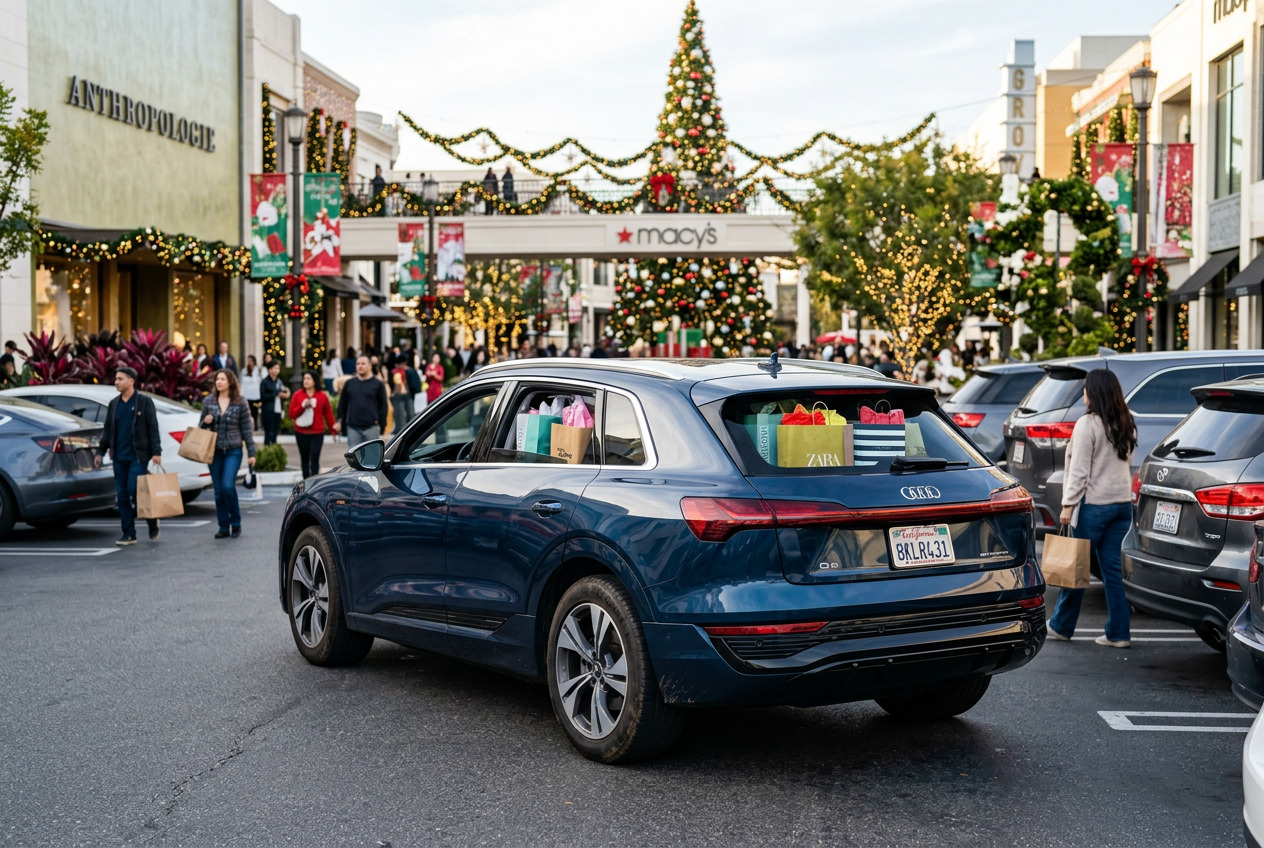
The holiday season is a bustling time for shopping, filled with finding perfect gifts, enjoying festive decor, and visiting crowded malls. But with the excitement of the season comes a heightened risk of vehicle break-ins and theft. Cars full of shopping bags, electronics, and other valuables become attractive targets for opportunistic thieves in busy parking lots and public spaces. That leads to a common concern for many California drivers this time of year: Does auto insurance cover theft?
The answer isn’t always straightforward. Depending on what was stolen and the type of coverage in place, protection could come from different policies. For example, while comprehensive auto insurance often covers vehicle theft or break-in damage, personal belongings stolen from the car may require homeowners or renters insurance coverage. Understanding these distinctions can prepare you for unexpected losses and help you make informed decisions during the holidays.
Does Auto Insurance Cover Theft? Understanding Comprehensive Coverage
Comprehensive auto insurance is specifically designed to cover non-collision-related losses, including theft and vandalism. If your vehicle is stolen or someone breaks into it during the holiday shopping season, comprehensive coverage may protect you from certain financial losses. However, it’s important to know that this type of coverage is optional under California law. If you lease or finance your vehicle, your lender may require it, but drivers with liability-only car insurance typically won’t have theft protection included.
What Happens If Your Vehicle Is Stolen?
If your vehicle is stolen, comprehensive coverage may compensate you based on the car’s actual cash value (ACV)—its market value minus depreciation—subject to your deductible and policy terms. For example, imagine you park at a shopping mall, excited to cross items off your holiday gift list, only to return later and find your car missing. If you hold comprehensive coverage, the policy could reimburse you for the loss, but the claim must meet all policy requirements.
It’s also worth noting that comprehensive coverage doesn’t include the cost of personal items taken from your car, which requires a different type of protection.
Does Comprehensive Insurance Cover a Broken Car Window?
What if a thief breaks your car window to access your belongings? Comprehensive insurance could help pay for the window repair, provided the damage falls under covered losses in your policy. That said, the repair cost must exceed your deductible to make filing a claim worthwhile. For instance, if repairing the window costs $400 but your deductible is $500, it may make more sense to pay for the repairs out-of-pocket rather than filing a claim.
Are Personal Belongings Stolen From Your Car Covered?
Here’s an essential distinction to remember: Comprehensive auto insurance protects your car, not what’s inside it. Shopping bags, gadgets, and other valuables left in your car generally won’t be covered under your auto policy if they’re stolen.
How Homeowners Insurance May Help
Homeowners insurance often includes personal property coverage, which may extend to belongings stolen off-premises, including from your car. For instance, if a homeowner leaves expensive holiday gifts in their vehicle and they’re stolen during a break-in, their homeowners policy may reimburse them for the loss, depending on policy terms, deductibles, and coverage limits. Keep in mind that high-value items may have sub-limits, meaning coverage for certain valuables like electronics or jewelry could be capped unless specifically insured.
Can Renters Insurance Cover Items Stolen From a Car?
Renters insurance works similarly when covering personal belongings stolen from a vehicle. A renter who loses their laptop after leaving it in a parked car during a quick holiday shopping trip may be protected under their renters policy. However, just like homeowners insurance, the coverage is subject to policy limits, exclusions, and deductibles. It’s a good idea to review your policy so you’re fully aware of what’s covered before heading out for your holiday errands.
What Should You Do After a Holiday Car Break-In?
If you experience a vehicle break-in during the holiday season, acting quickly and thoughtfully can streamline the claims process and reduce additional stress. Here are steps to follow:
Report the Incident and Document the Loss
- Move to a safe location: Focus on personal safety before taking any further action.
- Contact law enforcement: File a police report for documentation, which many insurers require for theft claims.
- Take photographs: Capture images of damage, such as broken windows or smashed locks.
- Compile a list of stolen items: Include descriptions, values, and receipts if available.
- Contact your insurance provider: Discuss which policies—auto, homeowners, or renters—may apply to different aspects of your loss.
- Review deductibles: Understand your out-of-pocket costs before submitting claims.
For example, a broken window may fall under comprehensive auto insurance, while stolen personal items might require a separate claim under a homeowners or renters policy.
Holiday Shopping Safety Tips to Reduce Vehicle Theft Risks
While no precaution is foolproof, a few simple steps can reduce the chances of becoming a victim of theft during holiday shopping:
- Keep shopping bags out of sight: Hide them in the trunk or use covers to obscure valuables.
- Take electronics and wallets with you: Minimize what you leave in the car.
- Park in well-lit areas: Choose spaces with high visibility.
- Double-check locks and windows: Ensure the vehicle is secure every time you leave.
- Avoid leaving items in your car for extended periods: Take your purchases home sooner rather than later.
- Stay alert in parking lots: Be aware of your surroundings to avoid risky situations.
- Activate car alarms or security systems: Make use of built-in or aftermarket theft deterrents.
By combining thoughtful prevention with the right insurance coverage, you can feel more prepared and confident this holiday season.
Review Your Auto and Personal Insurance Before the Holidays
Understanding your insurance coverage is key to protecting yourself financially before holiday shopping ramps up. Ask yourself these questions:
- Do I have comprehensive auto insurance?
- What’s my deductible for auto theft or break-ins?
- Does my homeowners or renters policy cover stolen items outside the home?
- Are there coverage limits for items like electronics or jewelry?
- How would separate deductibles apply across multiple claims?
- Am I aware of exclusions or restrictions in my policies?
- Do I need extra coverage for valuable belongings?
Answering these questions with the help of an insurance professional can clarify potential gaps and ensure you have the protection you need.
Protect What Matters Most With UNISERV
Auto insurance may cover vehicle theft, but personal belongings stolen from a car often require different insurance protection. Understanding the nuances of your policies is critical to safeguarding your finances, especially during the busy holiday season. Comprehensive auto insurance can provide peace of mind for vehicle theft and break-in damages, while homeowners or renters insurance may cover eligible stolen personal property. However, limits, deductibles, and exclusions affect what’s reimbursed, so preparation is key.
At UNISERV, we specialize in personalized insurance solutions that help you protect the things that matter most. Reviewing your coverage with our experienced team can help uncover protection gaps and give you confidence heading into the holiday season.
Looking for Insurance Guidance? Uniserv Is Here to Help
Whether it’s life insurance, home insurance, or business insurance, we offer a wide range of solutions to protect the things you