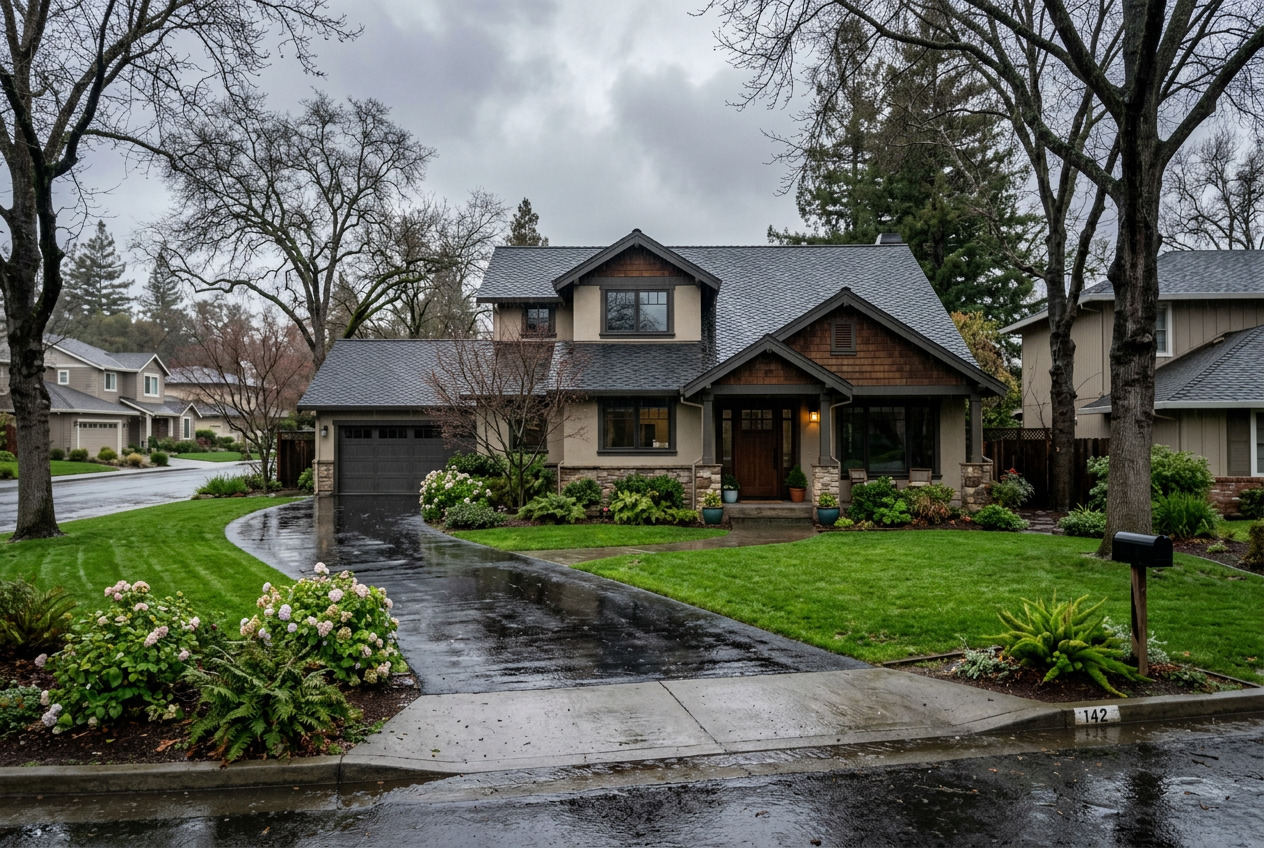
Cooler weather and seasonal storms can pose significant challenges for California homeowners. Heavy rainfall, strong winds, and fluctuating temperatures can easily expose vulnerabilities in a home, leading to costly damage without the proper preparation. While California’s winters vary by region, from heavy rain in coastal areas to snow in mountain communities, one truth remains—being unprepared can leave your property and finances at risk. Evaluating home insurance before winter is a critical step in safeguarding your home and ensuring peace of mind. By identifying potential coverage gaps and addressing vulnerabilities, homeowners can avoid unnecessary stress when winter storms arrive. Below, we’ll explore five seasonal risks every homeowner should address, along with actionable maintenance tips and key insights into how insurance responds to winter-related damages.
1. Roof Leaks and Storm-Related Roof Damage
Your roof serves as the first line of defense against winter weather. Seasonal rain and windstorms can exploit existing weaknesses, leading to issues like missing shingles, cracked flashing, or leaks from clogged gutters. Over time, minor roof problems can escalate, causing interior water damage that’s both inconvenient and expensive.
Does Homeowners Insurance Cover Roof Leaks?
Homeowners insurance may cover roof leaks and related interior damage if the issue stems from a sudden and accidental event, like a severe windstorm. For example, suppose a California homeowner faces a windstorm that rips shingles off the roof, allowing rain to seep into the attic. Depending on your policy, the damage may be eligible for coverage. However, leaks caused by ongoing maintenance neglect or long-term wear are generally excluded.
How to Prepare Your Roof Before Winter
Preventive maintenance can help reduce the likelihood of winter roof issues. Homeowners should:
- Inspect the roof for missing or damaged shingles and loose materials.
- Clear gutters and downspouts to ensure proper drainage.
- Check attic spaces for signs of moisture, such as water stains or mold.
- Schedule a professional roof inspection annually.
- Address any damage or vulnerabilities before heavy rainfall.
Taking these steps can protect your roof and limit the risk of avoidable winter insurance claims.
2. Fallen Trees and Branches During Winter Storms
Saturated soil and powerful winds common during California’s winter storms can lead to falling trees or branches, potentially causing property damage to roofs, fences, or outbuildings.
Does Home Insurance Cover Fallen Trees?
If a tree or large branch falls due to a covered peril, such as a windstorm, homeowners insurance typically covers the resulting structural damage. For instance, a windstorm might knock a tree into your home’s garage. Depending on your policy, repairs to the affected structure may qualify for coverage. However, coverage for tree removal without property damage is often limited or excluded.
Reduce Tree-Related Property Risks
To minimize risks related to falling trees, homeowners can:
- Inspect trees for visible decay or weakened branches.
- Trim overhanging or close-to-roof branches.
- Hire certified arborists to assess and maintain trees.
- Remove dead or diseased trees near structures.
Routine tree care can reduce storm hazards and protect your property from preventable damage.
3. Water Damage From Heavy Rain and Poor Drainage
Heavy rain during the winter season often places California homes at risk of water damage. Improper drainage or neglected maintenance can exacerbate problems, with water collecting near foundations, seeping through exterior walls, or intruding into basements or lower-level rooms.
Understand Water Damage Homeowners Insurance Coverage
While homeowners insurance may cover sudden and accidental water damage, such as rain entering the home due to wind-damaged windows, not all water-related losses qualify. Damage caused by slow leaks, poor maintenance, or surface flooding is typically excluded. Notably, flooding that results from rising water outside the structure usually requires a separate flood insurance policy.
Winter Drainage Maintenance Tips
To prevent water damage, homeowners should:
- Regularly clean and clear gutters and downspouts.
- Ensure drainage systems direct water safely away from the home’s foundation.
- Seal cracks in walls, windows, and weatherstripping.
- Evaluate walkways and exterior areas for potential drainage problems.
Addressing drainage issues can help homeowners avoid costly repairs and disruptions during the rainy season.
4. Plumbing Leaks and Frozen or Burst Pipes
Plumbing systems are often overlooked during winter preparations, yet they represent a significant source of potential damage. While freezing pipes are rare in most of California, mountain regions and areas prone to low temperatures remain at risk. Even in milder climates, aging or damaged plumbing systems can develop leaks.
Does Homeowners Insurance Cover Burst Pipes?
Homeowners insurance generally covers sudden and accidental water damage caused by burst pipes under certain conditions. Damage from neglected plumbing maintenance or ongoing leaks, however, is often excluded. Additionally, the cost to repair the pipe itself may not always be included.
Protect Your Plumbing Before Cold Weather
Reduce your risk of plumbing-related insurance claims with these steps:
- Inspect visible pipes for rust, leaks, or worn-out connections.
- Insulate pipes in areas exposed to colder temperatures.
- Repair dripping faucets promptly to avoid further damage.
- Leave indoor heating on at a consistent temperature during cold spells.
- Ensure you know the location of your main water shutoff valve for emergencies.
By addressing minor plumbing issues promptly, homeowners can prevent major water damage later.
5. Storm Damage to Windows, Fences, and Outdoor Property
Winter winds and storms often wreak havoc on outdoor areas, with broken windows, damaged fences, and detached outdoor fixtures being common property risks.
Review Coverage for Other Structures
Homeowners insurance typically covers damage to detached structures, such as fences or backyard sheds, when caused by a covered peril like storm-related wind damage. For example, if heavy winds knock over a fence, insurance may help pay for repairs depending on the policy. However, limits on coverage for detached structures and outdoor items like patio furniture vary by policy.
Prepare Outdoor Areas for Winter Storms
To safeguard outdoor property, homeowners should:
- Secure patio furniture, decorations, and lightweight belongings.
- Inspect and repair fences, gates, and loose fixtures.
- Reinforce window seals and weatherproofing.
- Store seasonal yard items in sheds or garages.
- Clear debris from drainage areas and walkways.
Advanced preparation can help minimize damage and streamline any potential claims process after a storm.
Document, Review, and Stay Prepared
Heading into winter, California homeowners should combine preventive maintenance with a thoughtful review of their insurance policies. Documenting your property’s condition and updating your coverage can help facilitate smoother claims if unexpected damage occurs. Remember, each policy differs in terms of coverage limits, exclusions, and deductibles. Understanding the finer details of your plan empowers homeowners to handle winter storms with confidence.
When ensuring your home is ready for the upcoming season, UNISERV can help. From personalized home insurance solutions to expert advice, we’re here to provide dependable protection for California families. Contact UNISERV today to review your policy, compare options, or explore tailored solutions for your insurance needs.